On Tuesday, October 20, 2026, SpaceX released its third-quarter financial results, reporting that Starlink’s global subscriber base reached 13.6 million customers following a quarterly net addition of 1.6 million users.
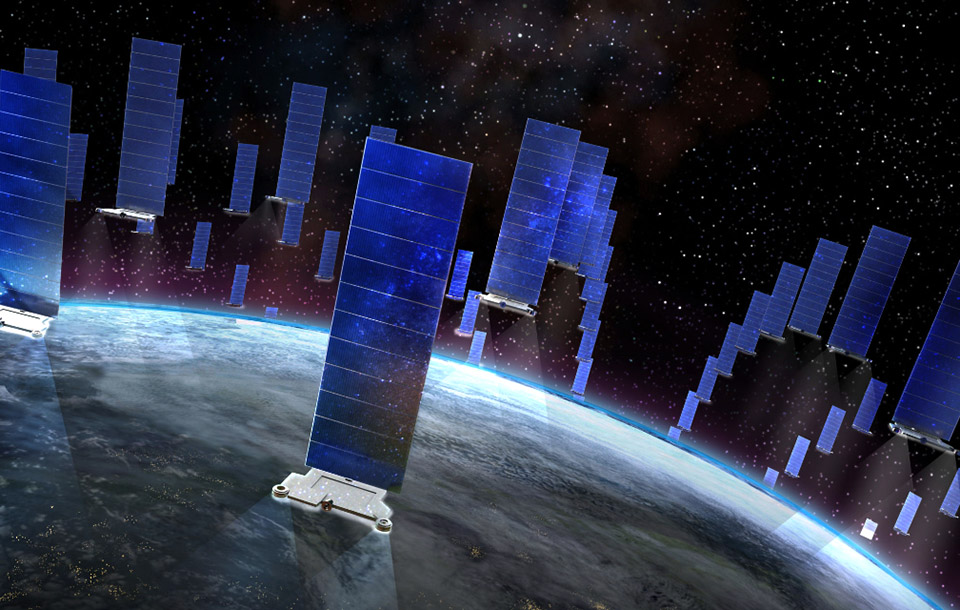
The earnings disclosure demonstrated connectivity revenue surging 69 percent year over year, reinforcing the low Earth orbit broadband constellation’s standing as the primary commercial revenue and cash engine of the aerospace company.
Contrasting Perspectives on Global Market Penetration
The rapid pace of Starlink’s user acquisition presents a compelling contrast when evaluated against institutional analysis published by GSMA Intelligence examining the commercial restructuring of the global connectivity landscape. In a specialized report examining how Starlink’s expansion reshapes satellite and mobile markets, the telecommunications trade association evaluated the company’s financial momentum through the lens of overall market share.
Citing SpaceX’s second-quarter metrics—which delivered $4.3 billion in connectivity revenue, up 66 percent year over year, alongside an operating free-cash-flow margin of 29 percent—the GSMA observed that Starlink’s commercial trajectory still has substantial ground to cover before fulfilling its broader market ambitions.
Annualized to roughly $17.2 billion, Starlink’s second-quarter revenue run-rate represents approximately 1.1 percent of the $1.6 trillion connectivity total addressable market (TAM) that SpaceX presented to institutional investors, as documented in previous analysis examining SpaceX’s financial metrics and public listing prospectus. Even as equity analysts track projections for Starlink’s subscriber base to reach between 35 million and 45 million by 2030, the GSMA highlights that expanding from high-value rural broadband into mainstream consumer mobility requires overcoming severe physical and economic barriers.
Terrestrial Femtocells and the 800 MHz Spectrum Foundation
To bridge the performance divide between orbital satellite beams and terrestrial cellular networks, SpaceX has teased plans to introduce a terrestrial femtocell deployment across the United States as an in-fill add-on to its orbital fleet. While GSMA researchers remain skeptical regarding the technical propagation constraints and operational economics of managing dense small-cell hardware at scale, the report emphasizes that SpaceX is systematically assembling the regulatory and technical assets required to operate a facilities-based nationwide wireless carrier.
The foundation of this terrestrial convergence strategy was established when SpaceX acquired Grain Management’s nationwide 800 MHz spectrum portfolio in early October. By acquiring up to 14 MHz of low-band spectrum below 1 GHz, SpaceX secures physical propagation attributes that overcome traditional satellite limitations, enabling signals to penetrate concrete buildings and dense urban foliage to connect directly with unmodified consumer smartphones.
Executive Analysis on the Telecom Frenemy Dynamic
The GSMA report evaluates the strategic tension between Starlink and incumbent terrestrial telecommunications carriers, characterizing the low Earth orbit provider as a complex industry “frenemy.” While commercial mobile network operators partner with Starlink to market supplemental non-terrestrial coverage in off-grid regions, mobile carriers are increasingly deploying coordinated defensive measures to prevent customer disintermediation.
“For telecoms operators, Starlink remains a ‘frenemy’, with a recent US mobile operator joint venture being an example of a defensive response,” the GSMA report highlighted. The analysis references the commercial initiative where AT&T, T-Mobile, and Verizon formed a joint venture to standardize direct-to-device connectivity across multiple satellite constellations, ensuring that terrestrial operators retain control over subscriber billing, operating systems, and core network interfaces.
Competitive Differentiation Across Sovereignty and Enterprise Moats
For legacy satellite fleet operators, the GSMA study indicates that attempting to compete against SpaceX purely on raw megabit delivery or consumer broadband pricing is an unviable long-term proposition. The report argues that sustainable market differentiation will increasingly center on operator integration, proprietary spectrum rights, specialized multi-orbit coverage, local regulatory compliance, and national data sovereignty.
As governments worldwide enforce strict data localization rules and seek sovereign non-terrestrial network alternatives to avoid single-vendor dependencies, established satellite operators and regional telco consortia are positioning themselves as trusted neutral-host partners. While SpaceX continues expanding its consumer subscriber base, the broader commercial satellite industry is orienting its business models toward secure defense communications, high-reliability enterprise trunking, and sovereign space architectures.