On Sept. 21, 2026, space market intelligence firm Novaspace released market data confirming that commercial geostationary (GEO) communications satellite orders reached 14 spacecraft announced year-to-date.
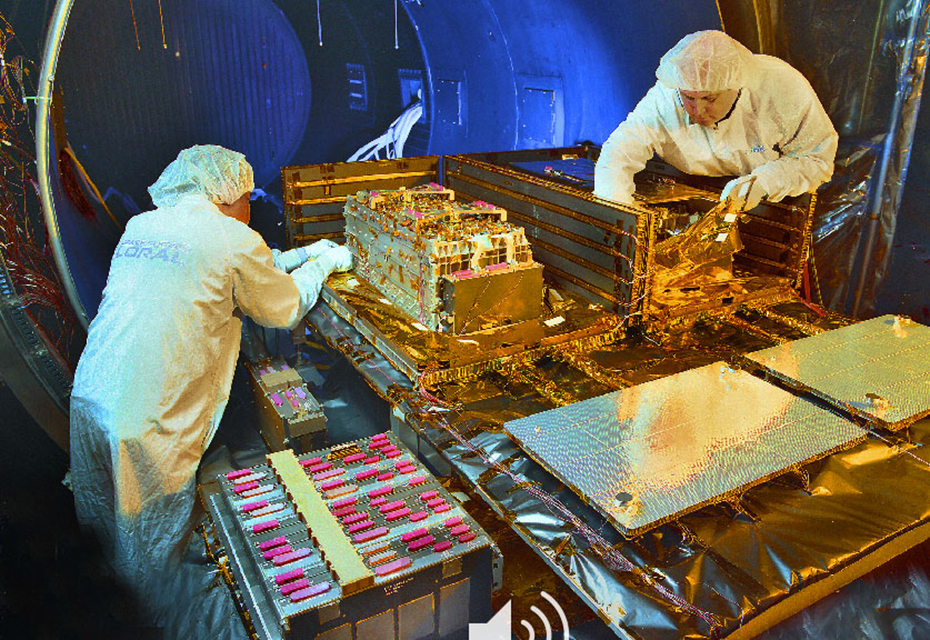
The figure marks a recovery from the 10 commercial GEO contracts signed during all of 2025 and represents the highest annual procurement volume for geostationary platforms since 2020.
Historical Procurement Context and Spectrum Catalysts
The expansion in commercial GEO satellite contracts follows several years of compressed procurement volumes, during which satellite operators diverted capital expenditure toward low Earth orbit (LEO) and medium Earth orbit (MEO) broadband constellations. The 14 orders recorded so far in 2026 represent the largest single-year commercial GEO commitment since the 18 awards announced in 2020 during the initial U.S. Federal Communications Commission (FCC) C-band spectrum clearing cycle.
A primary catalyst driving the current rebound is preparing infrastructure for upcoming regulatory spectrum reallocations. Three of the 14 commercial GEO orders placed in 2026 are directly tied to the upcoming upper C-band spectrum auction scheduled for next year. Satellite fleet operator SES is coordinating a larger fleet modernization strategy, planning seven GEO spacecraft in total to navigate the C-band spectrum transition while preserving broadcast and data relay services across regional markets.
Fleet Renewal Metrics and Payload Architecture
While low Earth orbit networks absorb high-volume consumer broadband traffic, commercial satellite operators continue replacing aging geostationary assets to maintain high-margin video distribution, mobility, and secure government communications links.
- 2026 Commercial GEO Orders: 14 spacecraft announced year-to-date
- 2025 Baseline Benchmark: 10 commercial GEO orders placed across full-year 2025
- Historical Peak Benchmark: 18 commercial GEO orders recorded in 2020
- Spectrum Clearing Driver: Three 2026 orders tied to upcoming upper C-band auction requirements
- SES Fleet Commitment: Seven total satellites planned by SES to facilitate the spectrum transition
Modern geostationary spacecraft feature flexible, software-defined payloads and digital transparent processors. Rather than deploying rigid, single-mission hardware, operators utilize reconfigurable GEO platforms that can adapt beam coverage, power allocation, and frequency plans in orbit to respond to shifting regional market demands.
Manufacturing Dynamics and Market Realities
Despite the 2026 order uptick, satellite prime contractors caution that the surge represents targeted fleet replacement and regulatory spectrum compliance rather than a permanent structural expansion of the commercial GEO sector. Satellite builders do not expect procurement rates to return to the historical averages seen a decade ago, when commercial operators routinely ordered more than 20 geostationary satellites annually.
The growth of multi-orbit communication architectures has permanently altered capital allocation across space telecommunications. Prime contractors have restructured manufacturing facilities to build standardized smallsat and medium-class platforms alongside traditional heavy geostationary buses, optimizing factory floors for lower production volumes of specialized, high-power GEO spacecraft.
Geostationary Market Outlook
As satellite operators finalize spectrum compliance plans ahead of next year’s upper C-band auction, additional replacement orders may be finalized through late 2026. However, overall commercial GEO procurement is expected to stabilize at moderate annual rates through 2027, with operators balancing geostationary broadcast payloads against growing investments in non-geostationary orbit (NGSO) constellation architectures.